
Buy Lido DAO
LDOPast performance is not indicative of future results. All prices are sourced from CoinJar Indices.
What is Lido DAO?
LDO is the governance token of Lido, the largest liquid staking protocol on Ethereum. It is not stETH, it is not staked ether, and holding it does not earn you Ethereum staking rewards.
That is the correction this page exists to make. Lido is a large and genuinely important piece of Ethereum infrastructure, and LDO is the token that votes on how it is run. Those are two very different things to own. Our guide to Ethereum covers the network Lido sits on, and our guide to staking explains the activity Lido packages up.
What Lido actually does
Staking on Ethereum normally requires 32 ETH and a validator you keep online. Lido removes both requirements. You deposit any amount of ETH, Lido pools it, professional operators run the validators, and you receive stETH in return.
stETH is the interesting part. It represents your staked position and it accrues rewards through a rebase, meaning your balance is recalculated, normally daily, when Lido's oracle reports updated validator balances. Rewards make the balance go up. Penalties and slashing can make it go down. Because a balance that changes on its own breaks the accounting assumptions of a lot of other software, Lido also offers wstETH, a wrapped version with a static balance that still tracks the same underlying value.
Lido charges a fee of ten percent of staking rewards, not of your deposit. According to Lido's documentation, that fee is split evenly: five percent of rewards to the node operators who run the validators, and five percent to the Lido DAO treasury.
Note where that money lands. It goes to the operators and to the treasury. It does not go to LDO holders.
What LDO is, and what it is not
It is a governance token. LDO votes on protocol parameters, node operator admissions, treasury spending and upgrades. It is not a claim on staked ETH. The token that represents staked ether is stETH, or wstETH in wrapped form. LDO represents neither. It does not accrue protocol revenue. There is no mechanism that routes Lido's fee income to LDO holders. Proposals to create one, including fee sharing and buyback programs, have been discussed in Lido governance over the years. Discussion is not implementation, and you should not price this token as though a revenue share exists. There is no LDO staking. Lido's staking product is for ETH. LDO itself is a plain ERC-20 governance token.
On supply, one billion LDO were created at launch, with roughly a third allocated to the DAO treasury and the remainder split between investors, validators, initial developers and users. Founding allocations were locked for a year and then vested. The treasury share is worth noting: a very large block of LDO sits under the control of the same governance system that LDO votes on.
Lido launched its Ethereum staking product at the end of 2020 and introduced LDO publicly in January 2021, created by a consortium of staking operators and crypto investors rather than a single company.
Who actually runs the validators
This is where Lido's decentralization claim gets tested, and where it has genuinely improved.
The original arrangement was the Curated Module, a permissioned set of professional node operators admitted by DAO vote. That is efficient and it is also a small group holding a very large amount of Ethereum's stake.
Two additions have widened it. The Simple DVT Module uses distributed validator technology so that a validator's duties are split across multiple independent parties rather than sitting with one operator. The Community Staking Module goes further and is permissionless: anyone who can run validators to the required standard and post a bond can join the operator set without needing a vote.
That is real progress, and it is fair to say Lido has done more work on this than most of its competitors. It is also fair to say the professional operator set still carries the bulk of the stake, and that Lido's decentralization is a direction of travel rather than an achieved state.
The concentration problem
Lido's share of all staked ETH grew to the point where it passed one third of the network.
That number is not arbitrary. Ethereum's consensus requires a two thirds supermajority to finalise blocks, so any single entity controlling more than a third has, in principle, the ability to prevent finality. Whether Lido is a single entity in that sense is exactly the argument, since it is a protocol coordinating many independent operators rather than one company running validators. Critics say the coordination is the problem regardless.
In 2022 the DAO voted on whether to self-limit Lido's share of staked ETH. LDO holders rejected it. The research forum thread where that was argued is still worth reading, because it is a clear example of token holders being asked to vote against their own growth and declining.
Lido's share has come down since its peak as competition increased and as more of Ethereum's stake moved elsewhere. The structural question has not gone away, and it remains the most common criticism of the protocol.
Dual Governance: what LDO can no longer do alone
This is the most significant change to LDO's position in years, and almost nothing written about the token reflects it.
Lido had a structural tension. LDO holders controlled upgrades. stETH holders carried the consequences. A vote by people holding one token could change the terms for people holding a different one.
Dual Governance, live on Ethereum mainnet since July 2025, addresses that. stETH holders can lock their stETH into a veto signalling escrow, which extends a dynamic timelock on DAO decisions. The more stETH is locked, the longer the delay. If locked stETH reaches ten percent of total supply, a rage quit is triggered, which blocks execution of governance decisions entirely while stakers exit the protocol. The signalling period can run for weeks, up to a maximum of forty five days.
The design is described in LIP-28.
Read as a holder of LDO, this cuts both ways. It is a serious answer to a serious criticism and it makes the protocol more defensible. It also means LDO governance power is now conditional. LDO holders can pass a proposal and still be prevented from executing it by people who hold a different token.
Lido V3 and stVaults
Lido V3 went live on Ethereum mainnet in January 2026, after being introduced in early 2025. Its main feature is stVaults, configurable staking vaults that let institutions and larger operators set their own parameters rather than using the single pooled product.
The strategic logic is that the pooled stETH model is not what every institution wants, and Lido would rather serve that demand than lose it. Whether that translates into revenue growth is not yet answerable, and for an LDO holder it is worth remembering that revenue growth does not automatically become token value in the absence of an accrual mechanism.
The Samuels case, and why LDO holders should read it
In November 2024, in a case called Samuels v. Lido DAO in the Northern District of California, a federal judge declined to dismiss a claim brought against Lido DAO over token sales. In doing so, the court accepted that the plaintiff had adequately alleged Lido DAO could be treated as a general partnership, and that several institutional investors could be liable as general partners because they had taken an active role in the DAO's management.
The implication is uncomfortable and it is not limited to Lido. If a decentralized autonomous organization is a general partnership under US law, then participants in it may carry the unlimited liability that general partners carry. That is a materially different proposition from owning a token.
Two qualifications matter. This was a ruling at the motion to dismiss stage, not a final determination on the merits, and the litigation has continued. And it concerns active participation in governance, not passive holding. But it is the clearest signal yet that the legal wrapper around DAO governance is not settled, and anyone buying LDO in order to vote should be aware that the question is live.
What are the risks of holding LDO?
No revenue accrual. Lido's fees go to node operators and the treasury. There is no mechanism paying LDO holders, so the token's value rests on governance rights and expectations rather than on cash flow. Governance power is now shared. Dual Governance gives stETH holders the ability to delay and ultimately block decisions that LDO holders have passed. Treasury concentration. A very large share of LDO supply sits in the DAO treasury, and how it is deployed is a governance decision. Concentration risk in the protocol itself. Lido's scale relative to Ethereum's total stake is a persistent criticism, has been the subject of a self-limit vote that failed, and could attract protocol level or regulatory responses. Legal uncertainty about DAO participation. The Samuels litigation raises unresolved questions about whether governance participants carry partnership liability. Smart contract and oracle risk. Lido depends on smart contracts and on an oracle reporting validator balances. Both are attack surfaces. Slashing and validator risk. Operators can be penalised or slashed, which reduces staked balances. That is a risk to stETH holders rather than directly to LDO holders, but a large incident would damage the protocol and the token together. stETH is not always exactly ETH. During the market stress of mid 2022, stETH traded at a sustained discount to ETH on secondary markets. Withdrawals now exist, which changes that dynamic, but exits still queue and are not instant. Product concentration. After winding down its Solana and Polygon products, Lido is an Ethereum-only business. Its fortunes are tied to one network and to the staking rate on it. Competition. Lido competes with other liquid staking protocols, with restaking products, and with exchanges offering staking directly. Volatility. LDO is not a stablecoin and its value moves sharply. No federal protection. Crypto assets are not covered by FDIC deposit insurance or SIPC protection. You should be prepared to lose everything you put in.
Buying LDO with US dollars on CoinJar
CoinJar has operated since 2013 and lists LDO against US dollars, so you can buy, sell and hold it without converting through another cryptocurrency first. Current charges are on our fees page, and live US dollar rates are on our cryptocurrency prices page.
CoinJar, Inc. is registered with FinCEN as a money services business and holds money transmitter licenses in a growing number of states, NMLS ID 2492913. You can check whether CoinJar operates in your state before signing up. Registration and licensing cover how CoinJar operates as a business. They are not an endorsement of any crypto asset listed on the platform.
How is LDO taxed in the US?
The IRS treats crypto assets such as LDO as property. A taxable disposal can occur when you sell LDO for US dollars, exchange it for another crypto asset, spend it or give it away, and gains or losses are generally reported on your federal return.
The IRS sets out its approach on its digital assets page. Our guide to pulling a transaction history for tax reporting covers the practical side. This is general information, not tax advice. Consider speaking to a qualified tax professional about your circumstances.
Bank transfer (ACH and wire), or crypto?
Buy Lido DAO instantly with your bank account via ACH or deposit with wire transfer. Easily buy with ACH, wire cash to your account, or swap one cryptocurrency for another in a single click.


How to buy Lido DAO with CoinJar
Start your cryptocurrency portfolio with CoinJar by following these simple steps.
Download the app
Get the CoinJar app on iOS or Android.
Create an account
Sign up and verify your ID – it only takes a couple of minutes.
Make a purchase
Buy Lido DAO and more than 60 other cryptos using ACH or wire transfer.
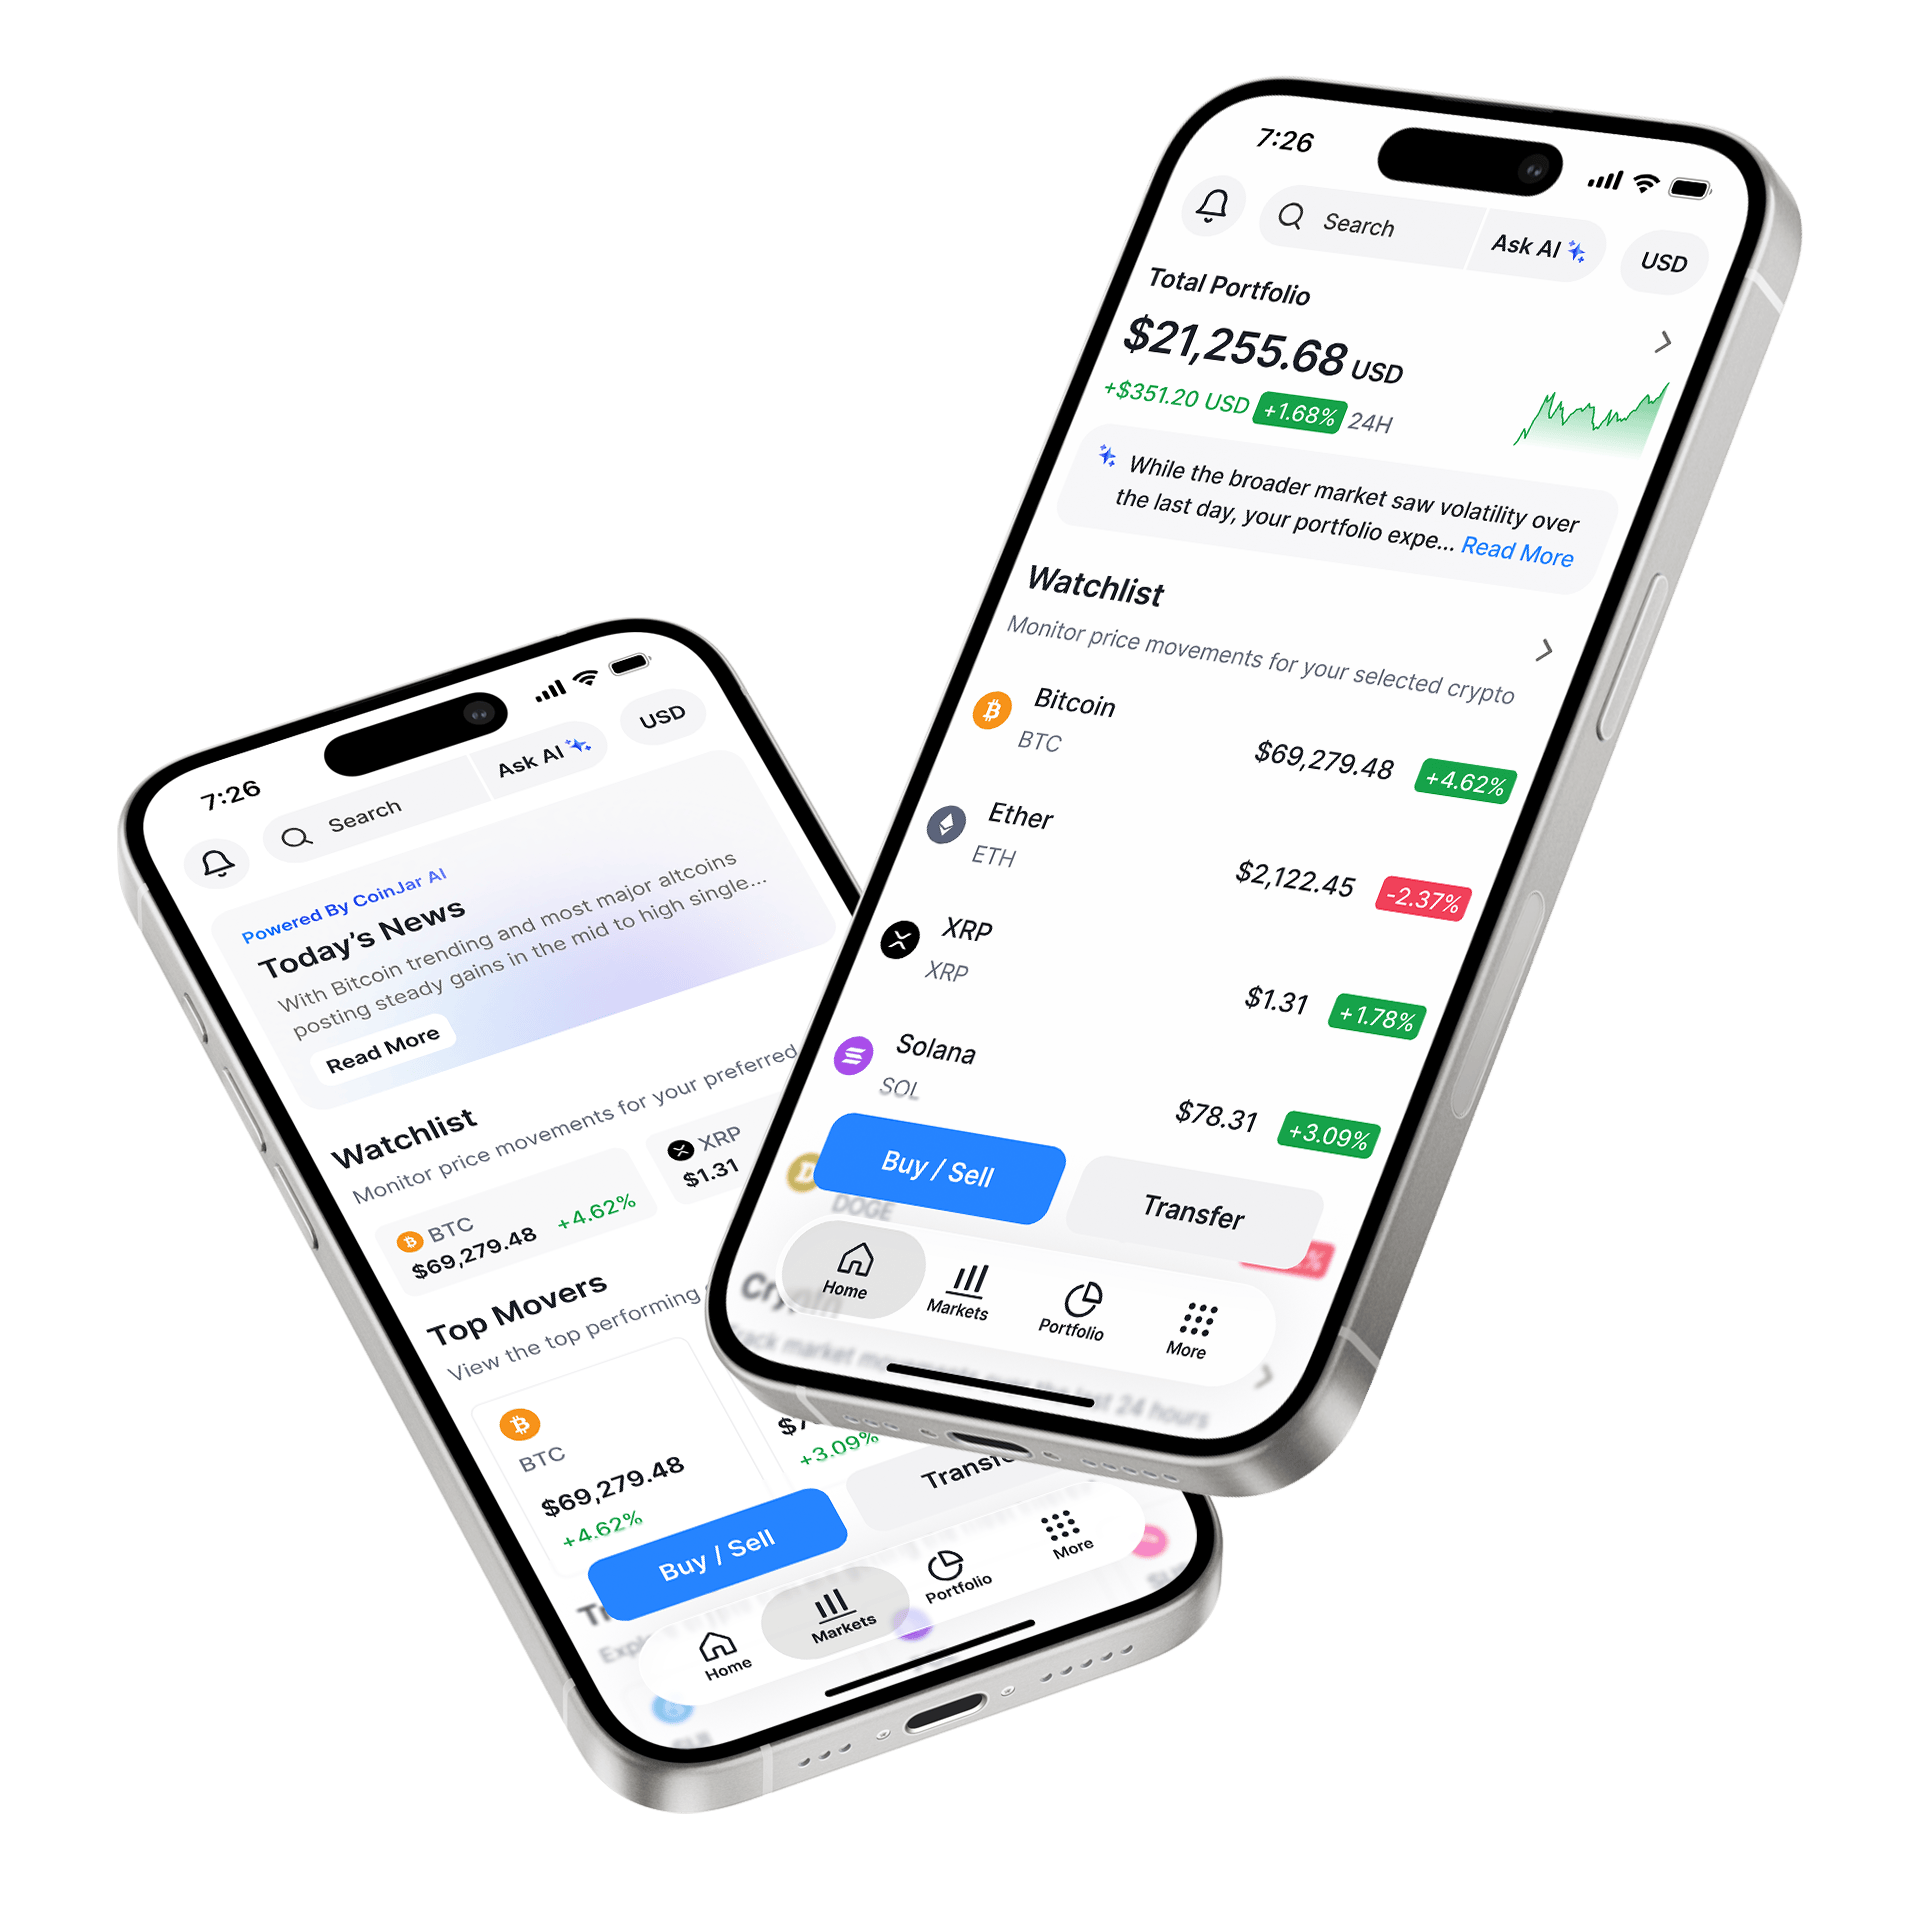
CoinJar App
Buy, sell and send your crypto with the favorite cryptocurrency app in the US.
Get the CoinJar appCoinJar App
Buy, sell and send your crypto with the favorite cryptocurrency app in the US.
Get the CoinJar app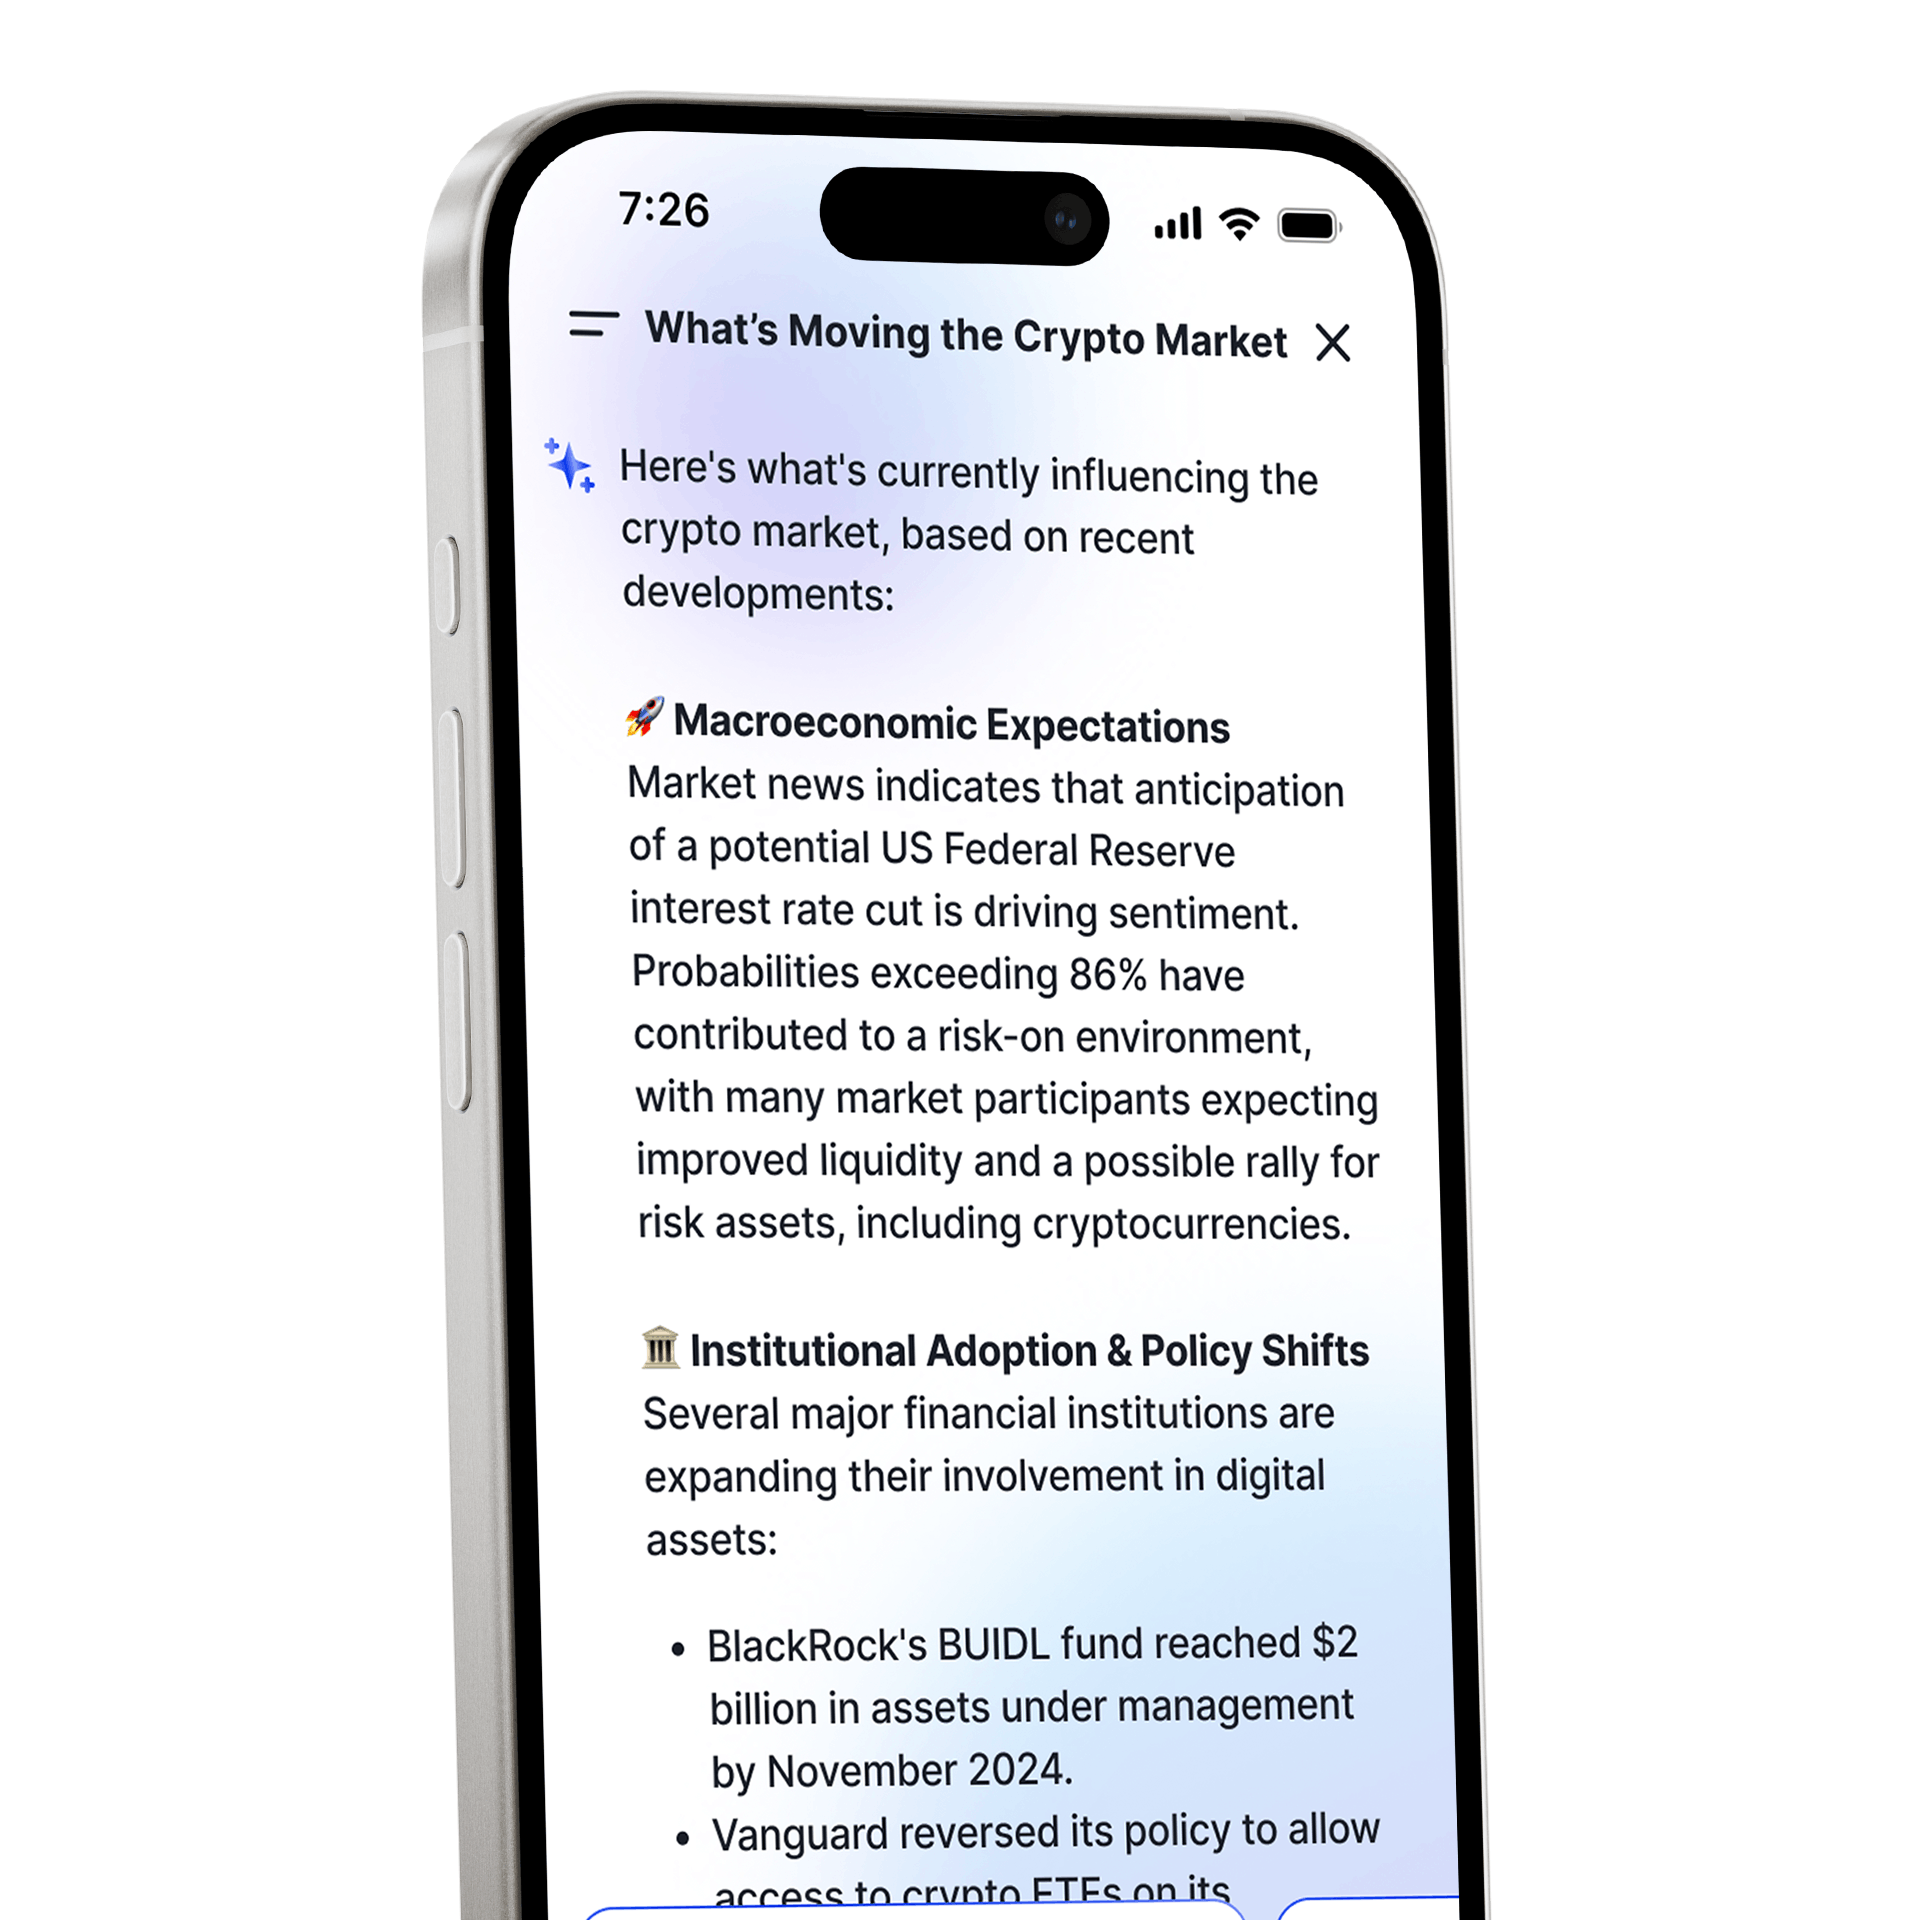
CoinJar AI
CoinJar AI understands your portfolio, tracks the market, and gives you insights that matter. Instead of searching for answers, simply ask a question to get the specific information you need.
Learn moreCoinJar AI
CoinJar AI understands your portfolio, tracks the market, and gives you insights that matter. Instead of searching for answers, simply ask a question to get the specific information you need.
Learn moreBuying, selling, and holding cryptocurrencies is subject to high market risk. The volatile and unpredictable nature of the price of cryptocurrencies may result in a significant loss. CoinJar, inc. is not responsible for any loss that you may incur from price fluctuations when you buy, sell, or hold cryptocurrencies. CoinJar, Inc. does not provide any investment, tax or legal advice; before making the decision to buy, sell or hold any cryptocurrencies, you should conduct your own due diligence and consult your financial, tax and/or legal advisor.
It is your responsibility to determine whether any investment, investment strategy or related transaction is appropriate for you according to your personal investment objectives, financial circumstances, and risk tolerance. Enter into a transaction only if you fully understand its nature, the contractual relationship into which you are entering, all relevant terms and conditions, and the nature and extent of your exposure to loss. Past performance is not a reliable indicator of future results. Geographic restrictions may apply. CoinJar does not endorse the content of, and cannot guarantee or verify the safety of any third party websites. Visit these websites at your own risk.

CoinJar
Get the app.