In March, the UK government formally announced plans to welcome and regulate digital currency activity in the UK. The promise of research funding, police training, and pragmatic regulation are welcome first steps, but to what end? The focus in this area tends to fall on questions of innovation, competition, crime, and jobs, but there may be something much broader at stake, namely the question of deciding what the money of tomorrow will look like.
Money at its core is a claim on resources, though we rarely see it in those terms. A pound coin or a twenty-pound note comes infused with notions of power, tradition, identity, and stability, and in the process its core function gets buried. Credit cards and bank accounts go some distance in stripping money back down to its bare functionality, but in a manner that complements rather than replaces existing ideas around money.
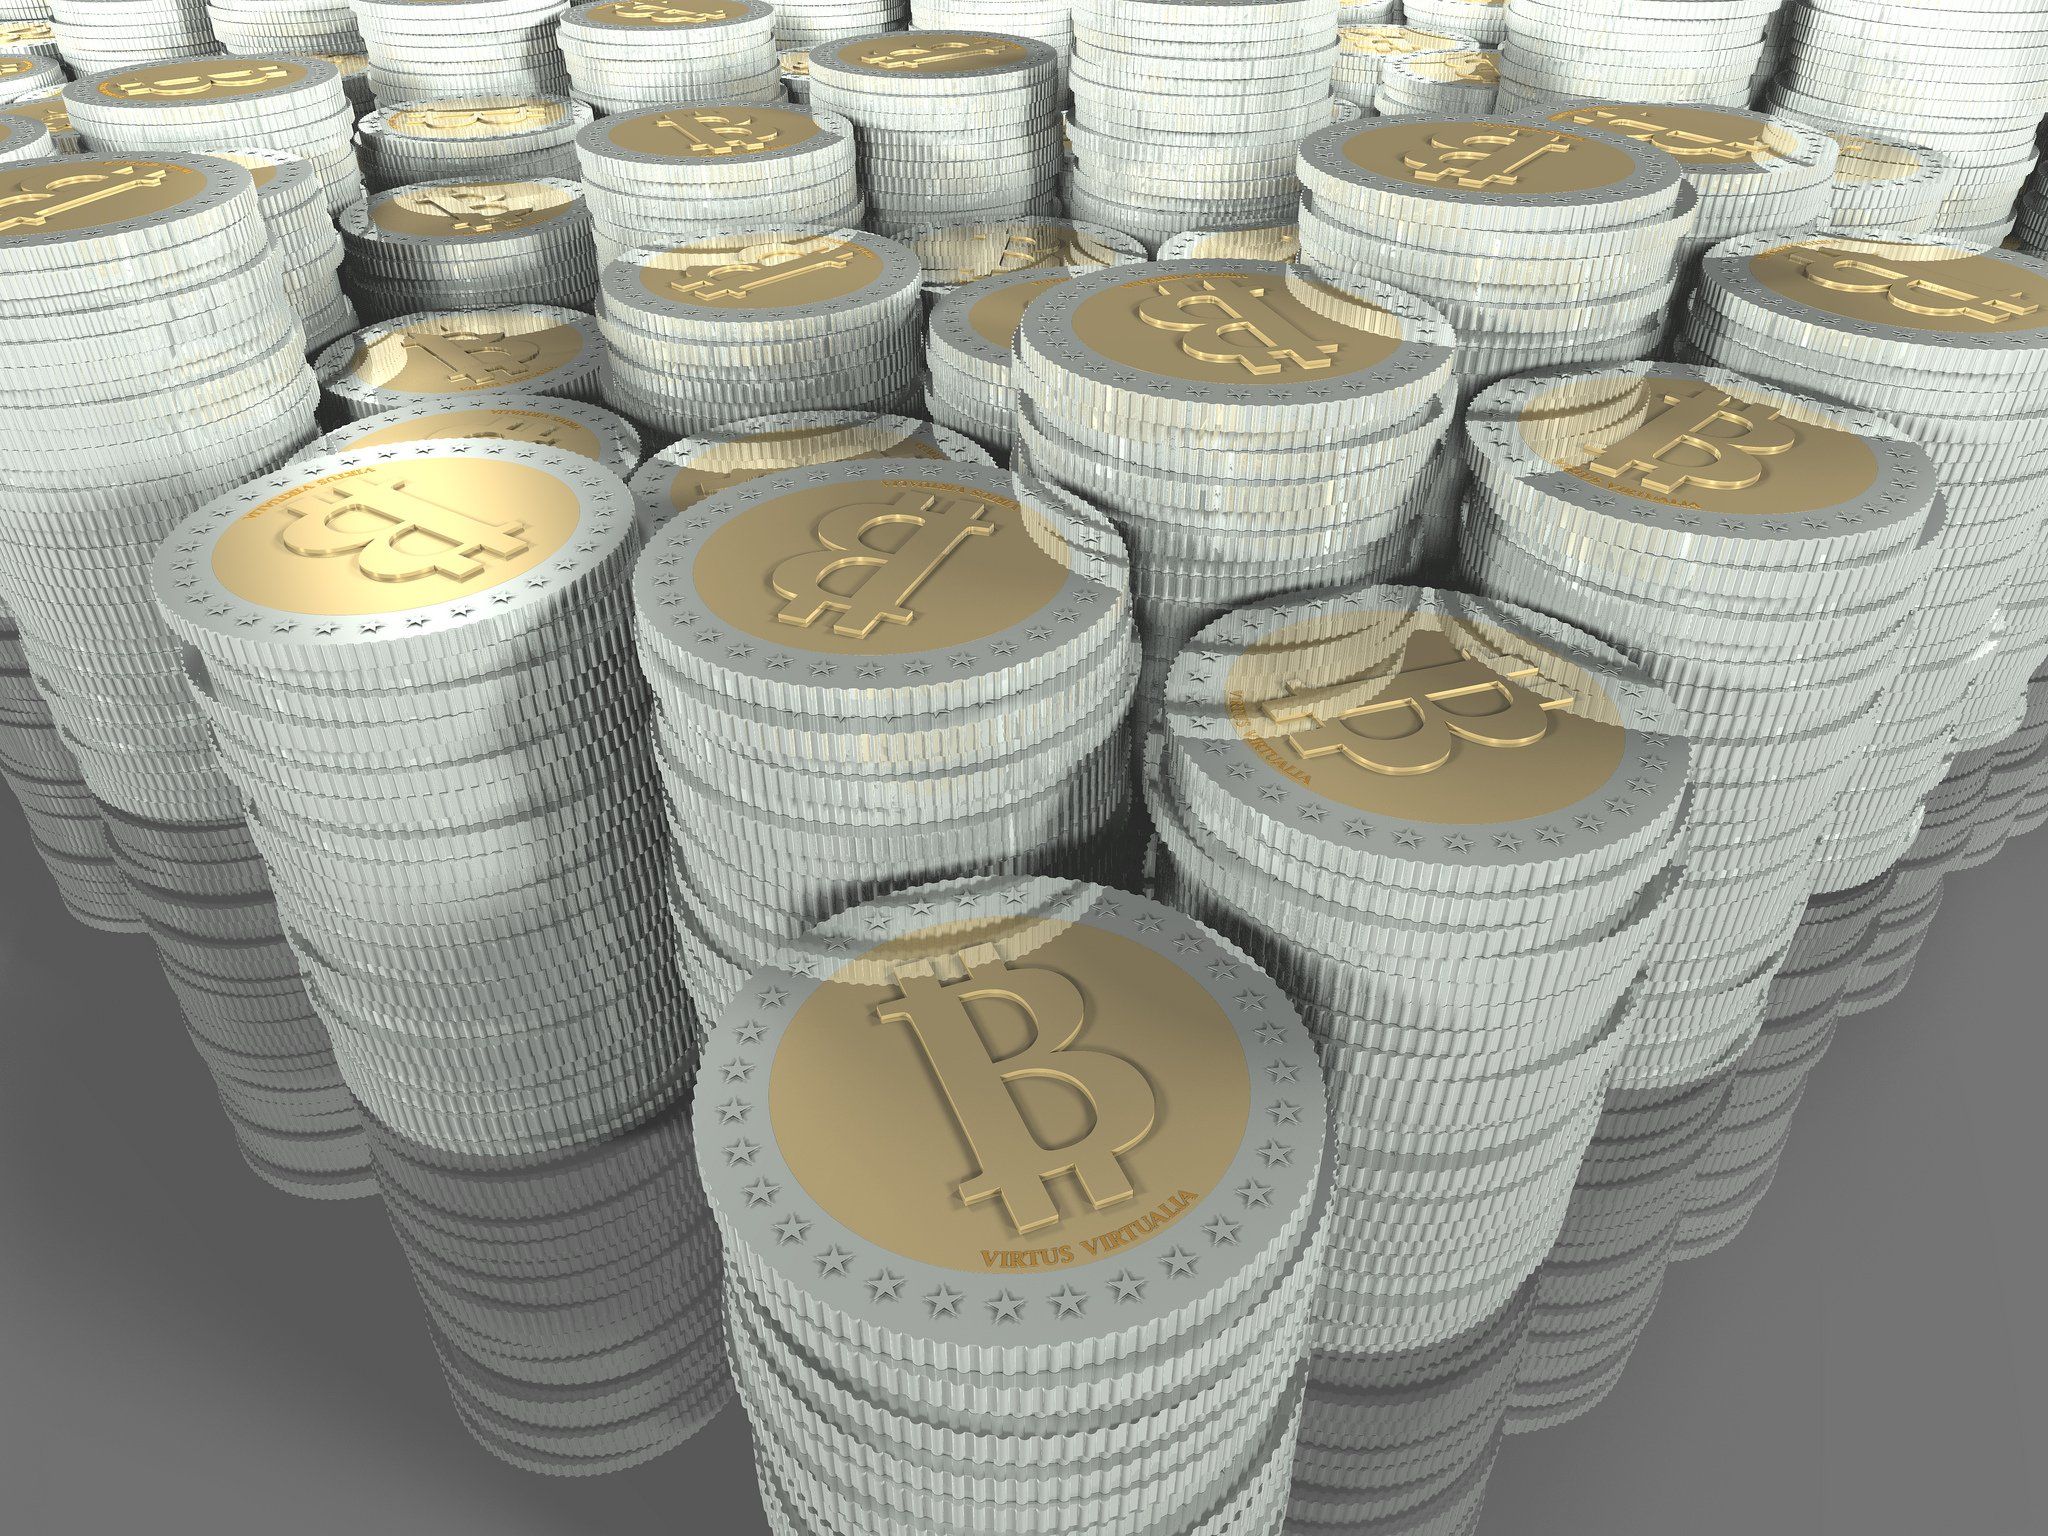
Community-issued digital currencies such as bitcoin are less accommodating, not least by their being ‘not backed by anything’. Each bitcoin is a numerical balance in a public ledger and nothing more: no gold reserve, no government pledge, no material referent of any kind, money flattened into a database.
The 2009 launch of bitcoin — an anonymous act of guerilla semiosis from one of the Internet’s darker corners — resulted in two interesting and opposing challenges to the imagination within its community of users. The first was that bitcoin itself was mystified, its digital tokens elevated with metaphors of gold, coinage, and mining, a public ledger praised as the biggest networking innovation since the Internet, and a compelling origin story with an enigmatic lead character. But in the process, for a substantial community of geeks and enthusiasts, ‘money’ more generally was de-mystified. The premise is simple: if money is just a database designed to manage claims on resources, surely there must be a smarter way to run that database? Suddenly every parameter is adjustable. That was not the case with precious metal or paper, the physicality of those forms of money making it easier to leave them unquestioned — this purple piece of paper is worth £20 the same way this pint of milk is worth 50p, nothing about either of these things prompts us to question the nature of value or ownership, it feels natural for something physical.
“…if money is just a database designed to manage claims on resources, surely there must be a smarter way to run that database?”
Once we are talking about tokens in a database the game changes entirely, because everything can be questioned. Consider the political tug-of-war that is the carbon credit system: How many carbon credits should we create? Who should get newly created credits? Should we let them expire? Or accumulate interest? Or maybe erode over time instead? Can a thing own a carbon credit? Once we make something materially fluid it becomes politically fluid as well.
Since Bretton Woods we have had a relatively rigid monetary order built on the US dollar as a global reserve currency, initially backed by gold, and later backed by little more than inertia. Over the last few decades the monetary space has largely been depoliticised — central banks have become largely autonomous, and governments have been stripped of their rights to influence money issuance or interest rates. Most of these changes were welcome, monetary policy remains arbitrary but at least decision making passed from election-focused politicians to a cadre of reassuringly boring technocrats.
The financial crisis prised the clamshell of monetary politics back open. There are two ways to increase the money supply: get banks to lend more (thus creating debt-based money) or issue new monetary tokens (aka ‘printing money’). As interest rates hit zero and post-crisis economies yearned for monetary stimulus, central banks found themselves contorting to do what was always presumed to be illegal — arbitrarily printing more money.
While the revival of central bank activism addresses the panicked and practical question — how can we stimulate the economy right now — the digital currency space has been gestating in the background, a political meditation on more fundamental questions around money, albeit now framed as a grand database that records our collective claims on resources.
When creating a claim on resources, who should initially get that claim? The monetarist consensus dictated that nobody had an unearned right to claim resources, and money created via the lending process should be sufficient. While largely successful, this also led to the systemically unstable link between money supply and debt levels. That bedrock of debt was a key ingredient in the financial crisis, and the quantitative easing which followed has left monetary consensus in tatters.
As a result, more heterodox solutions are rising to prominence. Neo-metallists (gold bugs) take the atavistic view that value is still something we dig out of the ground, while neo-chartalists (such as Positive Money) argue that money should be issued directly by an arm of the state. Both have seen a post-crisis resurgence. Meanwhile the bitcoin protocol awards newly created units of money to those who support its payment infrastructure, while other digital currencies have experimented with awarding newly created units to community members, a sponsoring organisation, renewable energy producers, or even forestry projects.
Token allocation is not the only big question posed by virtual currency schemes: should a new money system be managed by a central authority or a dispersed community? The former promises efficiency, the latter resilience and transparency. Is money a public good, infrastructure, or a competitive service? Should transactions be free? Or reversible? And what kinds of messages or programmatic functions should we allow people to latch on to their money?
But the greatest debate around digital money hinges on its relationship to identity and access, how do we find the balance between transparency and privacy? We can imagine two extremes — a perfectly anonymous digital cash system (still a largely theoretical proposition) — or a hyper-transparent social currency where all transactions, participants, and infrastructure are in the public domain. The challenge, as with all the other big questions, is finding where in the spectrum in between we want to land.
This article was originally posted on www.respublica.org.uk on 25 March 2015.
CoinJar Australia Pty Ltd ACN 648 570 807 is a registered Virtual Asset Service Provider (VASP) with the Australian Transaction Reports and Analysis Centre (AUSTRAC) in accordance with the Anti-Money Laundering and Counter-Terrorism Financing Act 2006 (Cth).
This material is general information only and does not consider your objectives, financial situation or needs. You should consider the Product Disclosure Statement and Target Market Determination (TMD) relating to the CoinJar Card product before making any decision. The CoinJar Card is a prepaid, reloadable Mastercard issued by EML Payment Solutions Limited ABN 30 131 436 532 AFSL 404131 (EML). CoinJar Australia Pty Ltd ABN 75 648 570 807 (Authorised Representative Number 1290193) is involved in the promotion and distribution of the Card and is a Corporate Authorised Representative of EML. Please consider the Financial Services Guide.
Apple Pay is a trademark of Apple Inc., registered in the U.S. and other countries. Google Pay is a trademark of Google LLC. Mastercard and the circles design are registered trademarks of Mastercard International Incorporated.
This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.